Net 27% Drop in Eurozone Mortgage Demand Exposes ECB's Soft-Landing Claim
October 28, 2026 · Frisian News
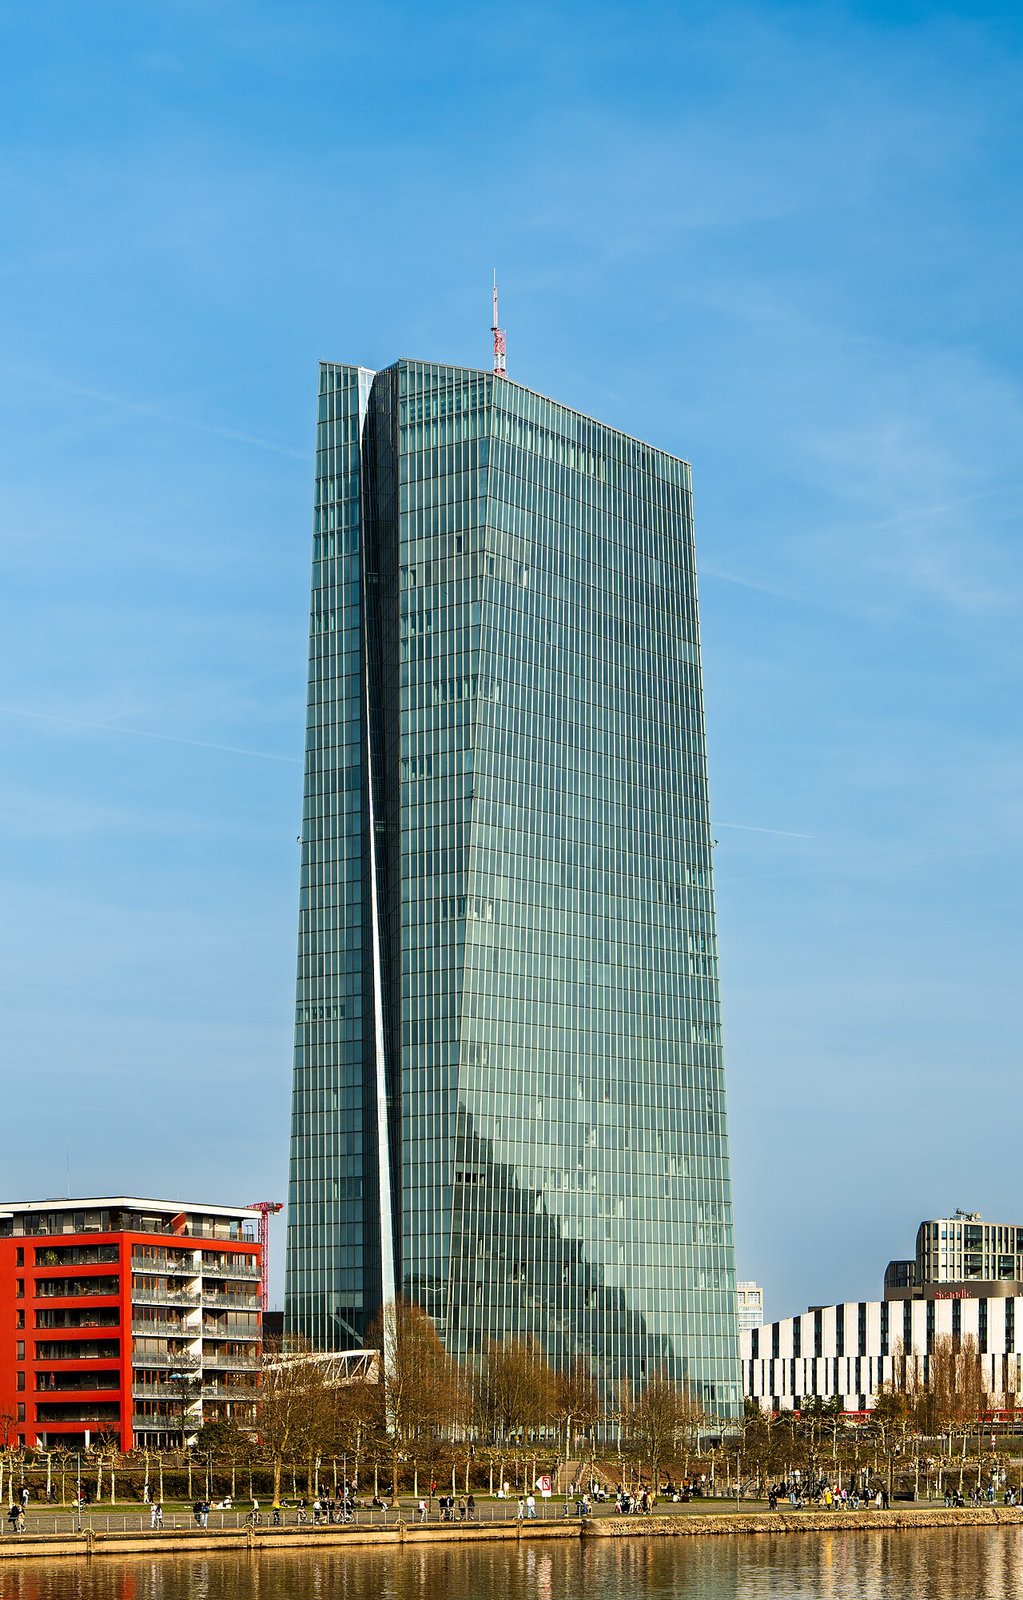
Photo: Wikimedia Commons
A net 27 percent of eurozone banks reported weaker mortgage demand in Q3 2026, more than double the previous quarter's reading and far above the 12 percent decline banks had forecast, according to the ECB's October bank lending survey.
A net 27 percent of eurozone banks reported weaker mortgage demand in the third quarter of 2026, according to the ECB's October bank lending survey published on October 27. That was up from the net 15 percent recorded in the previous three months and more than doubled the net 12 percent decline that banks themselves had forecast three months earlier. The survey covered 159 institutions across the euro area, with a 100 percent response rate.
The ECB said higher interest rates were the main driver of the collapse in home-loan appetite, followed by falling consumer confidence and worsening housing market prospects. The central bank raised its deposit rate to 2.5 percent in two steps this year, on June 11 and September 10, its first increases in three years, in response to an energy shock that pushed eurozone inflation to 3.3 percent in August, the highest since September 2023. Energy prices rose 14.3 percent over the year.
The damage spread well beyond households. Credit standards for company loans tightened by a net 9 percent in the third quarter, exceeding the 5 percent banks had expected, according to the ECB press release. Standards for consumer credit tightened by a net 14 percent, also beyond forecasts. Corporate loan demand fell by a net 6 percent, reversing a small rise in the second quarter and confounding expectations of a net 4 percent increase. Consumer credit demand slipped a net 2 percent against expectations it would hold flat.
Rejection rates climbed across every borrower category. The ECB's survey found the sharpest rise in consumer credit refusals. Access to retail funding deteriorated to its worst reading since the series began in 2011, and banks reported greater difficulty raising money on debt securities and money markets. They expect all of those funding sources to become harder to tap in the fourth quarter as well.
The ECB noted that the decline in mortgage demand was nonetheless "well below the peak recorded during the previous rate hiking cycle." That framing sits awkwardly alongside the forward-looking numbers. Banks now expect a net 36 percent fall in housing-loan demand in the fourth quarter and plan to tighten their mortgage approval criteria significantly over the same period, having left those criteria unchanged in the third quarter. Consumer credit demand is expected to drop a further net 14 percent in Q4.
What the rate rises have not done is bring house prices down. Euro area prices rose 4 percent in the year to the second quarter of 2026 and by 1.1 percent on the previous quarter, Eurostat data show. Across the European Union the annual increase reached 4.7 percent. Portugal led the way at 16.5 percent, followed by Bulgaria at 15.5 percent and Lithuania at 14.3 percent. Only Finland, Luxembourg and France recorded falls. Buyers now face credit that is harder to obtain and prices that keep rising.
The ECB's Governing Council met in Frankfurt on October 28 and 29. Economists polled by Bloomberg expected no rate move at that meeting, with a further increase pencilled in for December. The survey landed at a moment when access to retail funding had hit its worst point on record and when banks were braced for demand to fall further for housing loans and consumer credit, with corporate loan demand expected to remain broadly unchanged.
The European Commission created a housing portfolio for the first time in its current term, assigning it to Energy and Housing Commissioner Dan Jørgensen, and published its European Affordable Housing Plan in December 2025. Housing ministers are due to meet informally in Dublin on November 25 and 26 under the Irish presidency. Housing policy remains a national competence, which leaves Brussels with funding and coordination while borrowing costs do the work on household balance sheets.
Published October 28, 2026 · Frisian News